This guide explains how to evaluate a Payroll Solutions Portal for accurate, secure payroll processing and compliant reporting. It reviews what payroll portals typically do, why integration and auditability matter, and how to compare vendors without guesswork. You’ll also find requirements to verify, a practical selection approach, and objective FAQs to support decision-making.
Choosing a Payroll Solutions Portal is ultimately about reducing payroll risk while improving speed, consistency, and visibility. Start by confirming that the portal supports end-to-end payroll workflows (from employee data to pay statements), provides strong access controls, and produces audit-ready records that stand up during internal review or external audits. A payroll portal is not a “nice-to-have” UI layer; it becomes a core control point in your payroll process where inputs are validated, rules are applied, approvals are captured, and results are generated.
From an expert operations perspective, treat this selection as a controls project, not only a software purchase. Many payroll failures are not caused by arithmetic errors in calculations; they’re caused by process breakdowns: missing approvals, inconsistent rule configuration, ambiguous ownership of exception cases, or incomplete audit trails. The portal should help you move away from “tribal knowledge” (individual workarounds, undocumented steps, or hidden spreadsheets) and toward standardized, automatable, and traceable payroll operations. The best portals turn a chaotic set of month-end activities into a repeatable system with clear decision points and evidence.
Critical first checks: (1) integration with your HRIS and time/attendance sources, (2) configurable approval and exception handling, (3) secure role-based access, (4) compliance reporting and record retention features, and (5) clear implementation responsibilities between your team and the supplier. These five checks should appear early in your procurement process, ideally before you get drawn into demos that focus on aesthetics, user interface polish, or broad feature lists.
To make this practical, you can reframe the selection criteria as “control coverage” rather than “feature coverage.” Instead of asking “Does it have payroll approvals?” you ask “Where is the approval captured, which fields does it govern, how is it enforced, what happens if an approver is bypassed, and what evidence is retained?” Instead of asking “Can it produce payslips?” you ask “Can we prove payslips were generated from specific inputs and configuration versions, and can we reproduce the payroll run if we’re asked months later by internal audit, legal, or a regulator?”
Finally, align portal selection with your operating model: centralized payroll, regional payroll, blended HR/payroll ownership, outsourced payroll processing, or in-house compliance review. If your organization is multi-entity, multi-country, unionized, or heavily reliant on variable pay, you need a portal that handles complexity with strong governance rather than pushing complexity into manual steps.
A payroll portal is usually a web-based interface that centralizes payroll operations and related employee-facing information. While capabilities differ by vendor, very portals support some combination of:
Why this matters: payroll work is data-intensive and timing-sensitive. Errors can result from mismatched sources, incomplete approvals, unclear ownership, or inadequate change logs. A well-designed Payroll Solutions Portal helps standardize those inputs and decision points so payroll teams spend time on exceptions rather than repeated validation.
To ground the discussion in operational reality, payroll is a chain of dependencies. If the chain is weak at any link—data ingestion, validation logic, approval gating, calculation execution, or reporting/export—the overall system becomes unreliable. A portal attempts to reduce variability by making workflows explicit: what can be changed, by whom, under what conditions, and what the system will record as evidence. This is particularly important when employee changes occur frequently (joiners, leavers, transfers, address changes, benefit elections, pay rate adjustments) and when payroll cycles are short.
For objective context, many organizations also reference guidance from recognized bodies on controls and data protection. In the U.S., for example, the National Institute of Standards and Technology (NIST) Cybersecurity Framework is commonly used as a benchmark for evaluating security posture, while accounting and compliance practices often draw on standards such as SOC 1/SOC 2 reporting for service providers. (Consult your internal compliance and legal teams for jurisdiction-specific requirements.) The key procurement implication is simple: you should request evidence, not just assurances. Look for documented controls and third-party assessments that map to your expected control objectives.
Additionally, data privacy and retention expectations matter. Payroll systems often contain personally identifiable information (PII), tax identifiers, banking details (direct deposit), benefit plan data, and address history. A portal should therefore clearly define how data is encrypted in transit and at rest, who can access it, how audit logs are protected, and what the organization must do to retrieve or delete data according to applicable policies and regulations.
The portal should integrate with the systems that generate payroll inputs—typically HRIS, time/attendance, benefits administration, and sometimes accounting software. The key question is not whether integration exists, but whether it includes:
Expert lens: if integration is “set once” and rarely revisited, your payroll process can drift into risk. Look for tooling that supports data quality monitoring and versioned configuration. For example, a common integration failure occurs when the HRIS vendor changes a field format (a date field, currency code, or employment status enumeration) and the portal continues to ingest data using old assumptions. Without monitoring and version awareness, payroll can misclassify employees or apply incorrect tax treatment.
More specifically, you should evaluate:
Even if your HRIS and time system are accurate, integration governs what payroll actually sees. A dependable portal makes data governance tangible. It will show which records were imported, which validations succeeded or failed, and how exceptions were resolved. It will also provide a mechanism to correct data with appropriate evidence and approvals.
Finally, integration is not only about technical connectivity. It’s also about operational responsibilities. Ask: who owns the resolution when an employee record fails a validation rule? Does the portal assign a queue to HR, payroll operations, or the manager? Is there a defined escalation process if the exception is not resolved before the payroll cut-off?
Payroll data is high-impact information. A robust Payroll Solutions Portal typically includes:
Where this becomes operationally important: even with correct calculations, poor permissions can allow unauthorized edits, which increases both operational and compliance risk. Payroll is also attractive to internal threats because the data is sensitive and processes are time-bound. A portal should make it difficult to bypass approvals or modify payroll after cut-off without traceability.
In addition, you should evaluate how the portal handles common lifecycle and access complexities:
Also consider how the portal protects the confidentiality and integrity of audit logs. Audit logs should be tamper-evident or at least access-restricted to those who legitimately need them. If the portal provides “audit logs” but the same roles that can change payroll can also edit or delete logs, the audit trail does not provide much control value.
Finally, confirm how the portal handles security events. For example, what happens if a user fails authentication repeatedly? Are there alerts or throttling? Are there measures to prevent account takeover? While procurement may not require a full pen test, you should request security documentation sufficient for your security team to evaluate alignment with your corporate risk framework.
Payroll rules vary by company and often by location, union agreements, or specific benefit structures. Instead of relying on custom one-off processing, evaluate whether the portal supports:
Expert lens: the more your business changes (new hires, policy updates, reorganizations), the more you need a portal designed for safe change management. A portal that requires vendor intervention for every payroll rule update can create operational bottlenecks and increase risk if changes happen late or without adequate testing.
To assess configurability meaningfully, avoid generic demos. Instead, ask for configuration walkthroughs using real scenarios. Example scenarios to test in a demonstration or pilot include:
Approvals are another area where portals can differ drastically. A dependable portal not only offers approval screens; it enforces business rules about approvals. For example, it should:
Additionally, evaluate how the portal supports “exception queues.” In mature organizations, exceptions are managed like work items: assigned to an owner, tracked with status, due dates, and evidence. If the portal simply flags exceptions but does not provide workflow tools, payroll teams may still have to rely on email and spreadsheets—undoing the control benefits.
During internal reviews, month-end close, or compliance checks, you need to demonstrate that payroll was processed correctly and consistently. A strong Payroll Solutions Portal includes audit trails that show:
For reference, many organizations align vendor assessment to control frameworks like SOC 1/SOC 2 reports for service organizations and use these reports to understand internal control objectives. Your procurement and compliance teams should request and review vendor documentation appropriate to your region and reporting obligations.
Auditability isn’t only about storing logs; it’s about the quality and completeness of the logs. When internal audit asks you to explain a payroll run, they need to reconstruct “what happened” in a chronological narrative. This includes the sequence of events, the reason for changes, and the evidence of approvals. Therefore, you should look for:
Record retention is equally important. Requirements vary across jurisdictions and your internal policies. A portal should allow you to define retention schedules for audit logs and possibly sensitive documents. Also consider whether the portal supports legal holds or retrieval processes if records are needed for disputes or investigations.
Another practical point: audit logs must be usable. If logs are technically present but not searchable or understandable by payroll and audit teams, the organization ends up building additional processes to make audits possible. The portal should provide intuitive access to the audit evidence needed for reviews, ideally with filtering and run-level drill-down.
Payroll is not only a HR function; it feeds accounting and finance reporting. Look for:
Expert lens: reporting is where the “last mile” often fails—portals may calculate correctly but still make it hard to reconcile. Evaluate reporting accuracy through a pilot using historical payroll data. If your finance team spends hours massaging outputs, you haven’t eliminated risk—you’ve moved it.
To evaluate reporting, ask for:
Also assess usability and timeliness. A portal that provides rich reporting but only via complex ad hoc queries may not meet operational needs. The goal is to enable a controlled and repeatable month-end reconciliation process. If you need the portal to provide standard outputs on predictable schedules, the portal should include reporting workflows and permissioning so unauthorized users can’t access sensitive reports.
For audit and compliance, reporting also should be consistent. If the portal produces statutory reports or compliance exports, confirm that they match your payroll run outcomes and that they are reproducible. A portal that can generate reports but does not preserve the configuration and inputs used to create them undermines audit readiness.
Pricing for a Payroll Solutions Portal is rarely one universal number. Vendors commonly quote based on factors such as:
Because your request did not provide specific price figures, the top practice is to require a written quote with itemized assumptions. Avoid evaluating “headline pricing” alone; insist on clarity about what is included, what is optional, and how costs change as you scale.
To estimate cost responsibly, consider total cost of ownership (TCO). TCO includes not only licenses, but also:
Request a pricing model that clearly states what triggers cost increases. For instance, some vendors price based on “active users,” others on employee count, others on transaction volume (e.g., number of payroll runs or number of approval actions). Make sure the definition matches your operational reality. If you have multiple payroll entities or frequent retro adjustments, you want clarity on whether those activities increase costs.
Also ask about “hidden” costs such as:
Once you have itemized quotes, compare them using the same scope assumptions. A portal may appear cheaper until you include the features needed for your controls and reporting requirements.
Supplier capability matters as much as software features. During vendor due diligence, request:
Expert lens: a portal’s quality shows up during the difficult moments—retro corrections, missing time entries, rapid policy changes, and end-of-year or end-of-period close.
To make supplier evaluation concrete, you can request evidence tied to these moments. For example:
Also evaluate the supplier’s delivery maturity. A strong vendor can provide a structured implementation methodology: discovery, design, configuration, integration testing, user acceptance testing, training, go-live support, and post-go-live stabilization. Weak vendors may propose a minimal plan that shifts too much work onto your team or leaves key controls ambiguous.
Look for clarity about what is “out of scope.” In payroll, out-of-scope items can become risk. For instance, if the vendor won’t handle specific compliance exports, you need clarity on who will. If the vendor won’t provide a mechanism for audit evidence retention, you need to know whether you will accept that limitation.
Finally, check contract terms related to security, privacy, and service levels. Consider negotiating service level agreements (SLAs) or support response times that reflect payroll urgency. Payroll failures typically have deadlines; a portal that responds within “business hours” might be insufficient for urgent payroll-impacting issues during cut-off windows.
Below is a practical process you can run internally to compare suppliers objectively and reduce selection bias.
To further reduce bias, assign scoring weights based on your risk and control needs. For example, if your organization has complex union rules and frequent retro pay, integration and exception handling might deserve higher weight than employee self-service aesthetics.
Another best practice is to run “scenario-based evaluation.” Rather than evaluating features in isolation, you test the portal’s behavior in a sequence that resembles real payroll operations. A scenario-based evaluation might include:
During the scenario, observe not only outcomes but also process quality. Does the portal enforce approvals? Does it log changes? Can you reproduce the run? Does it make the exception owner aware of what evidence is needed? These are the questions that matter operationally.
Finally, ensure your pilot has realistic data volume and includes edge cases. Many pilots fail because they only include “happy path” data. A dependable portal should behave reliably under abnormal conditions, and your test should prove that.
| Evaluation area | What to compare (capability signals) | Sources to request from supplier | Conditions / requirements to verify |
|---|---|---|---|
| Payroll workflow coverage | End-to-end processing, approvals, exception handling, pay statement generation | Workflow diagrams, sample screenshots, process documentation | Run simulation with scenarios (retro pay, missing time, manual adjustments) and confirm audit logs capture changes |
| Integration readiness | Supported HRIS/time systems, mapping approach, reconciliation tools | Integration guides, API/integration specs, data mapping templates | Test pilot confirms correct field mapping and validation rules; define ownership for data correction |
| Security controls | RBAC, MFA/SSO options, encryption, session security, audit logging | Security overview, control statements, relevant third-party reports (as applicable) | Least-privilege roles defined; logging retains enough detail for internal review; user lifecycle (joiner/mover/leaver) process is documented |
| Auditability | Traceability for calculations, approvals, data edits, exports | Audit log samples, retention policy description | Ability to reconstruct “what happened” for a payroll run; retention aligned with your internal policy |
| Reporting and exports | Payroll registers, accounting exports, variance reporting | Report catalog and sample outputs | Reconciliation outputs match your accounting requirements in pilot testing |
| Implementation and change management | Migration approach, configuration governance, training plan | Implementation schedule, acceptance criteria, training materials | Defined milestones and sign-off steps; configuration changes go through controlled review and testing |
| Support model | Incident handling, release cadence, escalation paths | Support SLA overview, incident response process | Confirm coverage hours, escalation procedures, and how urgent payroll-impacting issues are handled |
Implementation is only the beginning. To get reliable outcomes from a Payroll Solutions Portal, payroll leaders should standardize how teams use it:
To expand these practices into a more mature operating model, consider building a “controls calendar” alongside your payroll calendar. A controls calendar includes recurring evidence collection tasks: who validates time import completeness, who reviews exception queues, when approvals are locked, and what checks are performed before final payroll submission.
Operational excellence also requires consistency in how the portal is used across pay periods. A common failure mode is inconsistent behavior: one payroll cycle resolves exceptions manually while another cycle routes everything through workflow. The portal should encourage consistent behavior by providing templates, required fields, and guided steps. Still, you must enforce consistency through governance and training.
Another key practice is to formalize ownership for each type of exception. Exceptions often originate in different places: HR changes, time entry failures, data mapping issues, benefit elections, or configuration mismatches. Without defined ownership, exceptions stall or are resolved incorrectly. Assign an owner group (HR operations, payroll operations, time management) and define escalation rules. The portal should support these queues and provide status visibility.
Also, implement post-run review practices. After payroll is processed, conduct a review to identify patterns in exceptions and near-misses. For example, if a particular validation rule triggers frequently for a certain region, you may need to adjust data upstream in the HRIS or update a rule configuration to match policy. A portal can provide metrics and reports to support this continual improvement.
Finally, plan for period-end and year-end complexity. Even when day-to-day payroll is stable, end-of-year reporting and statutory updates create a different risk profile. Ensure the portal’s configuration governance supports timely updates, testing, and approval ahead of deadlines. Confirm that retention policies cover end-of-year artifacts and that audit trails remain accessible for the required retention period.
Payroll operations are shaped by local employment practices, terminology, and documentation expectations. Even when the portal is global, the adoption path must match your operating culture. For example:
If you operate “nearby” multiple sites or departments, you can treat each as a mini-implementation: map how requests flow internally and configure exception paths accordingly. That approach tends to reduce surprises during the first few payroll cycles.
Localization also includes operational language and workflow translation. A portal may support multiple languages, but operational adoption depends on how accurately the portal’s labels reflect the organization’s understanding. If the portal uses different terminology for “overtime,” “allowances,” “retro pay,” or “termination,” managers and employees may misunderstand required evidence or forms. This can create mis-submissions that later require correction and approvals.
Additionally, consider differences in banking practices, tax identity handling, and document requirements. For example, certain regions may require specific documentation for bank account changes or may have stricter processes for verifying tax-related updates. The portal’s workflow capabilities should support these local requirements, ideally via configuration rather than custom one-off manual processes.
Another nuance is that payroll processes may vary by employee type (full-time, part-time, contractors, seasonal workers) and by business unit. Even within one country, you might have different pay frequency, different overtime eligibility, or different deduction structures. A portal must support those variations using controlled rule configurations and access controls so that each business unit receives correct treatment.
From an organizational standpoint, adoption is also about how teams handle change. If managers are expected to approve time adjustments, ensure they understand what they are approving. Many payroll errors occur because approvers do not know what “evidence” is expected or what the consequences are of approving incorrect data. Training and in-portal guidance can reduce these errors.
Finally, align localization with data privacy rules. If the portal stores payroll data across regions or if access is managed globally, ensure your security and compliance approach aligns with jurisdiction requirements. A portal should clearly document data residency options or limitations, as well as encryption and access patterns.
A Payroll Solutions Portal is typically used to manage payroll workflows, centralize payroll inputs, handle approvals and exceptions, generate pay statements, and provide reporting and audit trails for payroll processing.
In practice, it often also becomes the operational “front door” for changes to payroll-related data—pay rate changes, employment status updates, time correction requests, and approval events. Many organizations also use it to enable employee self-service, which can reduce inbound workload and increase transparency for employees regarding pay statements and deductions.
Run a pilot using historical payroll scenarios or realistic test cases. Compare portal outputs against known results, including edge cases like retro pay and corrections. Require reconciliation outputs that your finance team can verify.
To make evaluation rigorous, test multiple “angles” of accuracy: calculation accuracy (does it compute correctly), data mapping accuracy (does it ingest and interpret correctly), workflow accuracy (are approvals enforced), and reporting accuracy (do exports reconcile to accounting). Vendor claims are not sufficient; your pilot should require measurable evidence.
At minimum, look for role-based access control, secure authentication options (e.g., MFA/SSO where feasible), strong audit logging, and a documented user lifecycle process (joiner/mover/leaver). Ensure permissions align with separation of duties.
Non-negotiable also includes the ability to protect the confidentiality of exports and reports, control access to sensitive employee data, and maintain audit log integrity. A portal without strong separation of duties is effectively a manual system with a digital skin, which does not reduce risk.
In very organizations, yes—because payroll accuracy depends on consistent source data. If integration isn’t available, manual data entry increases error risk and can weaken auditability.
If integration is partial, ask how partial integration affects your control objectives. For example, if time entries must be re-entered manually, what validations exist? Who reviews them? How is the evidence stored? If you accept manual inputs, you must compensate with stronger approvals, validations, and reconciliation controls.
Ask for an implementation plan with milestones, security and access documentation, integration specifications, report samples, support SLAs, and any relevant third-party assurance materials appropriate to your compliance expectations.
You can also request documentation that shows how configuration changes are governed and how you would validate those changes in a test environment before they go live. For a payroll portal, change management documentation is as important as security documentation.
Pricing often depends on employee volume, selected modules, implementation/migration scope, integration work, and support coverage. Request itemized quotes so you can compare total cost of ownership rather than only a base fee.
Ensure you understand the definitions behind pricing metrics, such as what counts as an “active user,” whether contractors are included, how multiple entities are priced, and whether retro adjustments increase transaction-related costs.
Timelines vary by data readiness, number of entities, integrations, migration complexity, and approval workflow needs. Request a detailed schedule with acceptance criteria and a realistic pilot timeline before signing.
Implementation length is not only a project management concern—it directly impacts risk. If implementation compresses testing and user training, operational stability may suffer during the first payroll cycles. A strong supplier will propose a timeline that includes adequate testing for payroll workflows, exception handling, security roles, and reporting exports.
Frequent causes include incomplete system integration, unclear approval responsibilities, insufficient data governance, weak separation of duties, under-scoped pilot testing, and lack of training for managers or employees who submit changes.
Another frequent challenge is insufficient “process design” time. People buy portals but do not redesign workflows. When the organization’s approval paths, exception queues, and responsibilities aren’t redesigned to match the portal’s capabilities, adoption becomes inconsistent and errors rise.
Often yes. Many organizations begin with one business unit or one payroll cycle, validate integration and audit flows, then expand. The exact approach depends on your supplier’s implementation model and your internal readiness.
Phased adoption can reduce risk but introduces its own challenges, such as ensuring consistent configuration across phases and preventing “shadow processes” during the transition. A good rollout plan clarifies what runs where, when approvals switch, and how historical data is handled.
Use controlled change management for configuration updates, schedule recurring data quality checks, keep access roles current, and ensure your team is trained to operate the portal consistently across payroll cycles.
Maintainability also depends on documenting configuration decisions and keeping a record of why certain rules were implemented. When staff changes occur, documentation helps prevent reintroducing old workarounds or misconfigurations.
A Payroll Solutions Portal should help you process payroll with repeatable controls: accurate inputs, transparent approvals, secure access, and audit-ready records. By combining a structured comparison process—piloting integrations, verifying security and reporting outputs, and requiring clear implementation responsibilities—you can select a portal that supports dependable payroll operations well beyond the initial rollout.
When you evaluate portals with a controls-first mindset, you shift the focus from “can it do payroll?” to “can it do payroll reliably, repeatably, and verifiably?” That shift is what ultimately reduces risk. It also improves operational speed because teams spend less time chasing issues and more time resolving true exceptions. The right portal becomes a control framework that supports your payroll team—day after day, payroll after payroll, audit after audit—until payroll operations become predictable rather than fragile.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
The Guide to Car Trading
Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
Understanding Organisational Behaviour Slideshare
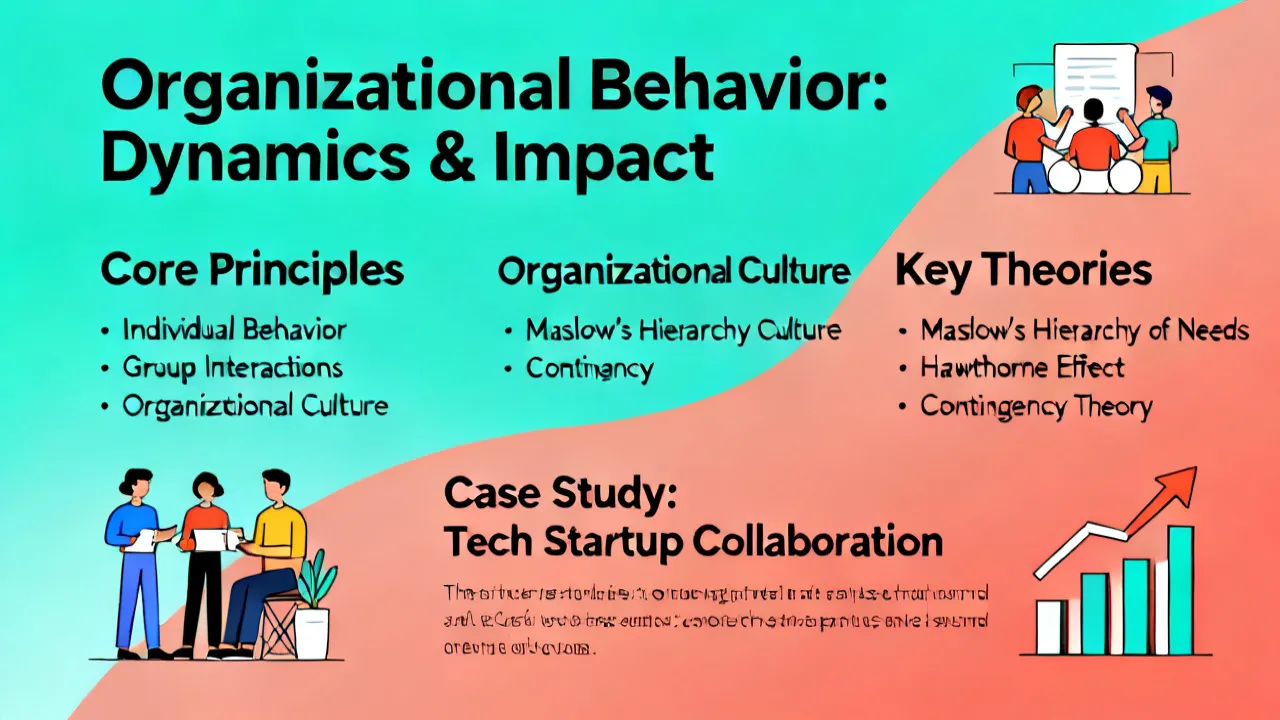
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Mastering Organisational Behaviour Dynamics
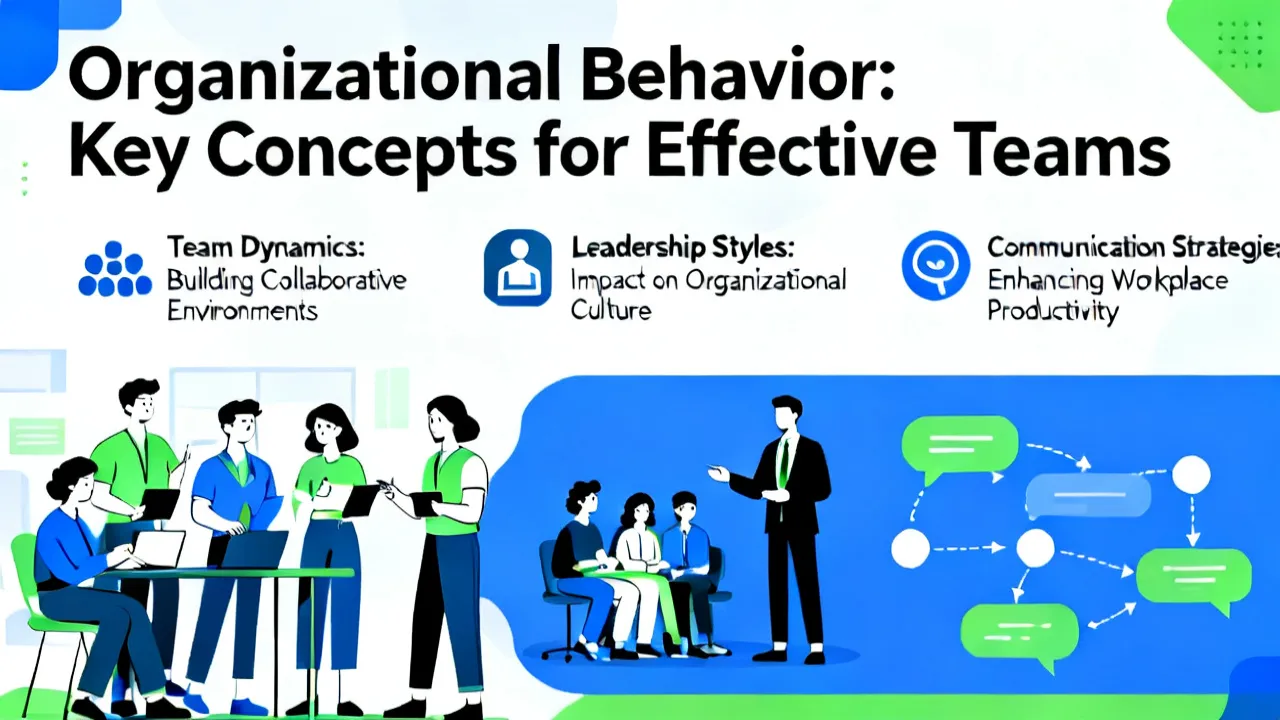
This guide explores the intricacies of Organisational Behaviour through Slideshare resources. It delves into the study of how people act within groups and organizations, offering insights into the psychological and sociological factors that influence workplace dynamics. This comprehensive analysis examines theories and practices to enhance understanding and improve corporate environments, supported with FAQs and expert perspectives.
Mastering Organizational Behavior
This comprehensive guide explores the significance of organizational behavior within corporate settings, providing a deep dive into theories and practical applications as depicted on popular platforms like Slideshare. Organizational behavior studies the impact of individuals, groups, and structures on behavior within organizations to improve an organization's effectiveness.